Time Series Analysis: Concept, Additive and Multiplicative Models
1. Nature, Concept & Managerial Utility of Time Series Analysis
In business analytics, a Time Series is defined as a set of statistical observations arranged in chronological order. Whether monitoring daily stock prices, monthly retail revenues, quarterly corporate earnings, or annual GDP figures, the independent variable is always continuous time $t$, and the dependent variable is the numerical business metric $Y$.
"A time series is a set of statistical observations arranged in chronological order. Its primary analytical purpose is to identify and isolate historical patterns to forecast future outcomes with quantified probabilistic confidence."
"A time series consists of data which are analyzed with respect to time. The mathematical decomposition of time series aims to isolate the diverse forces that simultaneously act upon business phenomena."
Core Strategic Objectives in Corporate Management
Modern corporate executives employ time series decomposition for four vital operational functions:
- Continuity of Forces: The economic and institutional forces that dictated historical data will continue to govern future periods in an orderly manner.
- Decomposability: Total variation in the series is not homogeneous but can be mathematically partitioned into four distinct, measurable forces $T, S, C, I$.
- Equi-Spaced Chronology: Observations must be recorded at strictly uniform time intervals (e.g., hourly, daily, weekly, monthly, or quarterly).
2. Mathematical Decomposition Models: Additive vs. Multiplicative
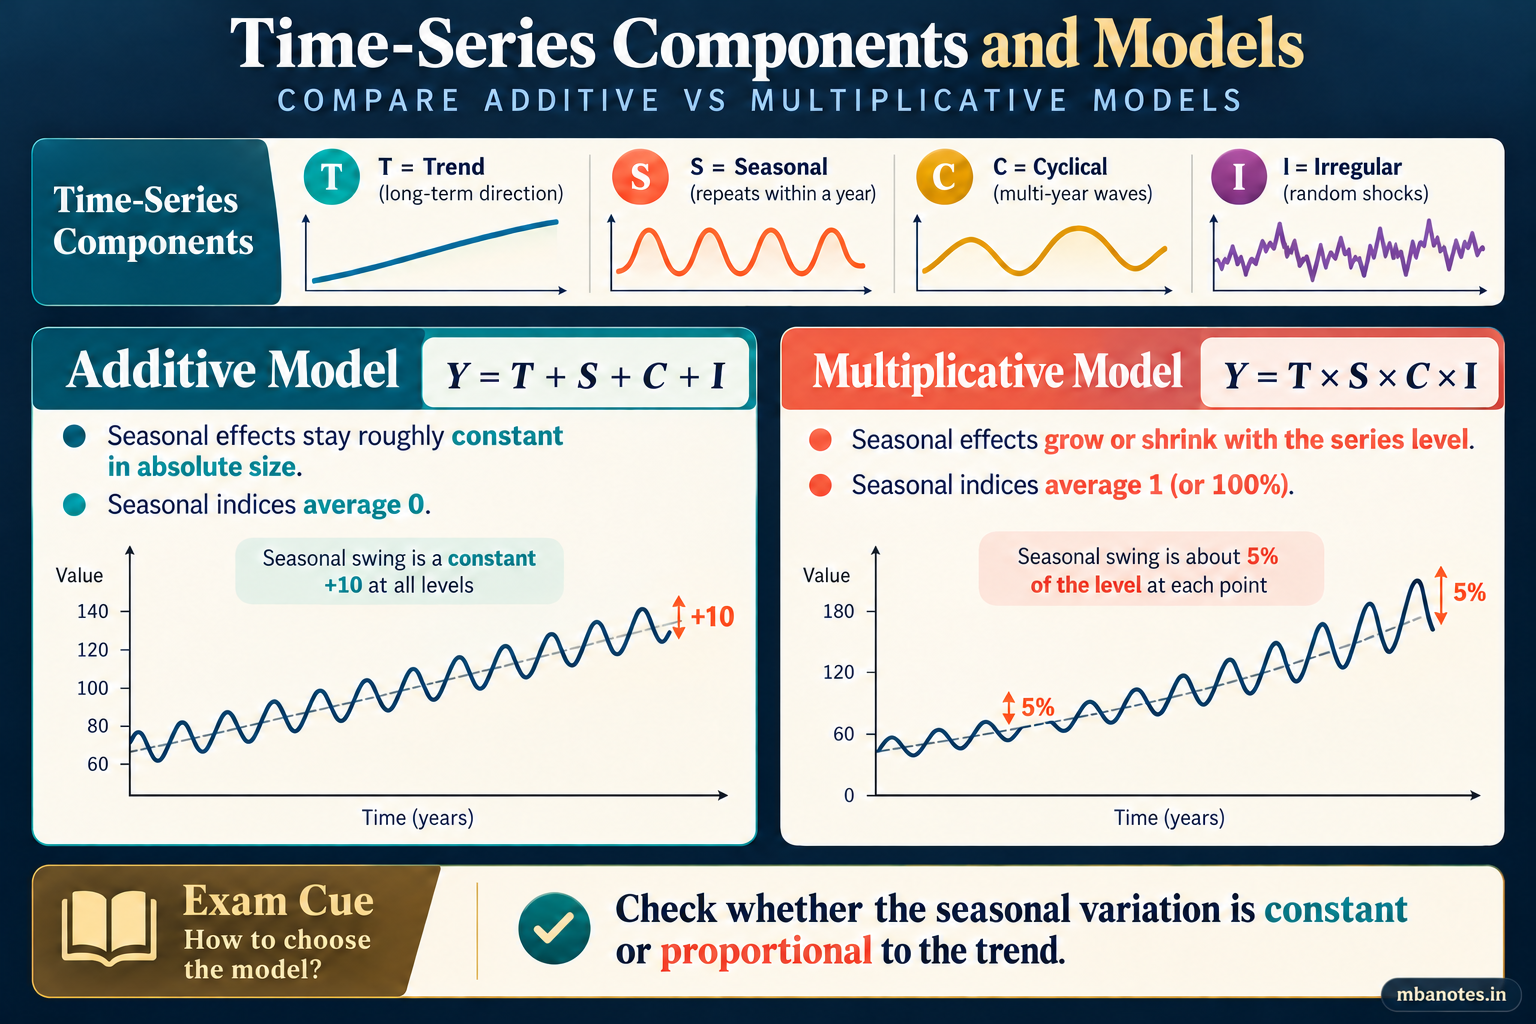
In time series econometrics, observed data $Y_t$ at time $t$ is assumed to be an aggregate result of four underlying forces: Secular Trend $T_t$, Seasonal Variation $S_t$, Cyclical Fluctuation $C_t$, and Irregular Shock $I_t$. The two fundamental mathematical formulations used to combine these components are the Additive Model and the Multiplicative Model.
Model A: The Additive Framework
Independent ComponentsThe Additive Model posits that the observed value is the straightforward algebraic sum of its four constituent elements.
Core Mathematical Assumptions:
- Mutual Independence: The four components operate completely independently of one another. The magnitude of seasonal or cyclical variation does not depend on whether the trend is rising or falling.
- Uniform Physical Units: All four components $T, S, C, I$ are measured in the exact same original physical units as the observed data (e.g., metric tonnes of cement, thousands of units sold, or rupees).
- Constant Oscillation Band: Seasonal variations oscillate around the trend line with an absolute, invariant width over time. Even if total company sales triple over a decade, seasonal variation remains a constant (+5,000) units in Q4 and (-5,000) units in Q2.
- Annual Balancing Property: Over a complete annual period (12 months or 4 quarters), seasonal deviations exactly cancel each other out:$$\boxed{\sum_{i=1}^{k} S_i = 0}$$
Model B: The Multiplicative Framework
Industry Standard • Scale-DependentThe Multiplicative Model assumes that the observed value is the product of its components. This is the predominant model used in modern business, finance, and economic forecasting.
Core Mathematical Assumptions:
- Interdependence & Proportionality: The four components interact dynamically. Seasonal and cyclical fluctuations are not absolute amounts but relative percentages or indices of the underlying trend level $T_t$.
- Measurement Scale: While Trend $T_t$ is expressed in original physical units (e.g., ₹ Crore), Seasonal $S_t$, Cyclical $C_t$, and Irregular $I_t$ factors are pure dimensionless indices or decimal multipliers (e.g., $S = 1.30$ indicates a 30% positive seasonal surge).
- Expanding Envelope (Trumpet Pattern): As the enterprise grows and trend $T$ scales upward, the absolute seasonal swings expand proportionally. A 30% Diwali boost on a ₹100 Crore base generates a ₹30 Crore surge, but on a ₹500 Crore base, it generates an expanded ₹150 Crore surge.
- Annual Balancing Property: Over a full annual cycle of 12 months or 4 quarters, the arithmetic mean of the seasonal indices equals 1.0 (or 100%):$$\boxed{\frac{1}{k}\sum_{i=1}^{k} S_i = 1.0 \quad \iff \quad \sum_{q=1}^{4} S_q = 400\%}$$
3. Master Comparison: Additive Model vs. Multiplicative Model
Understanding the distinction between Additive and Multiplicative models is among the most frequently tested concepts in university MBA exams (AKTU Section B & C). The comprehensive structural comparison matrix below highlights every operational parameter.
| Comparison Parameter | Additive Model | Multiplicative Model |
|---|---|---|
| 1. Governing Formula | $Y_t = T_t + S_t + C_t + I_t$ | $Y_t = T_t \times S_t \times C_t \times I_t$ |
| 2. Component Interaction | Assumed strictly independent. No interaction effect among factors. | Interdependent. Seasonal and cyclical swings scale dynamically with trend. |
| 3. Units of Measurement | All 4 components expressed in identical original physical units (e.g. ₹, kg, units). | Trend in physical units; (S, C, I) are dimensionless ratios, indices, or percentages. |
| 4. Amplitude of Fluctuation | Constant absolute amplitude over time regardless of whether trend doubles or halves. | Expanding/contracting amplitude (funnel shape) directly proportional to trend magnitude. |
| 5. Annual Seasonal Sum | $\sum_{i=1}^k S_i = 0$ | $\sum_{q=1}^4 S_q = 4.0$ (or 400% for 4 quarters) |
| 6. De-seasonalizing Formula | $\text{Deseasonalized } Y = Y_t - S_t$ | $\text{Deseasonalized } Y = \frac{Y_t}{S_t} \times 100$ |
| 7. Real-World Corporate Applicability | Rare. Suited only where market scale is stationary (e.g. municipal water usage, regulated utility quotas). | Extremely High (>95%). Suited for growing commercial enterprises, e-commerce, FMCG, auto sales, and stock prices. |
4. Step-by-Step Solved Numerical: Decomposing Quarterly Enterprise Sales
To master university numerical examinations, let us solve an end-to-end practical decomposition problem comparing the two methodologies.
A consumer durables manufacturer records sales of Rs. 1,440 Lakh in Quarter 3 (Diwali festive quarter). The established secular trend value for this quarter is calculated as Rs. 1,200 Lakh, and the historical seasonal index for Q3 is 1.15 (or +15%). A temporary logistics strike caused an irregular shock of Rs. -30 Lakh.
Calculate:
(a) The expected sales under the Additive Model (assuming seasonal variation is +Rs. 180 Lakh and cyclical effect is +Rs. 40 Lakh).
(b) The isolated cyclical-irregular factor under the Multiplicative Model.
(c) The deseasonalized sales value for the quarter under both models.
In the additive model, components add together linearly:
Given values: $T_t = 1200$, $S_t = +180$, $C_t = +40$, and $I_t = -30$:
Conclusion: The anticipated sales under the additive framework is Rs. 1,390 Lakh.
In the multiplicative framework: $Y_t = T_t \times S_t \times (C_t \times I_t)$. To isolate the combined cyclical-irregular ratio $C_t \times I_t$, we divide actual sales by the trend and seasonal components:
Substituting actual sales $Y_t = 1440$, $T_t = 1200$, and $S_t = 1.15$:
Conclusion: The combined cyclical and irregular forces boosted quarterly sales by 4.35% above the baseline trend-seasonal projection.
Deseasonalizing removes recurring seasonal calendar effects to reveal the true underlying business trajectory:
6. Real-World Corporate Case Study: Maruti Suzuki India Ltd.
Festive Season Inventory Modeling: Additive Failure vs. Multiplicative Precision
Context: Maruti Suzuki India Ltd. (MSIL) historically experiences its largest sales spike in Quarter 3 (October–December), driven by the Navratri, Dhanteras, and Diwali festival seasons. In early 2018, MSIL's commercial forecasting team utilized an Additive Decomposition Model that assumed festive seasonal variation was a fixed additive volume of approximately +35,000 vehicles above baseline quarterly trend.
Actual Q3: 288,000 units
Seasonal Boost: +38,000 (+15.2%)
Additive Target: 420k + 35k = 455,000
Actual Demand: 504,000 units
Severe Shortage of 49,000 vehicles!
Multiplicative Index: 1.18 (+18%)
Forecast: 420k × 1.18 = 495,600
Forecast Accuracy: 98.3%!
The Analytical Revelation: As Maruti's nationwide dealership footprint, production capacity, and market base scaled from 2015 to 2021, consumer festive demand did not remain static in absolute numbers. Instead, festive purchasing expanded proportionally as a 18% multiplier of the company's expanded commercial footprint. The Additive model underestimated consumer demand by nearly 50,000 units, leading to 6-to-8 week customer waiting periods and dealership inventory stockouts.
7. High-Frequency AKTU Previous Year Exam Questions (PYQs)
These questions have appeared consistently in AKTU MBA Business Statistics & Analytics examinations over the past 5 academic cycles.
Section A: Short Conceptual Questions (2 Marks Each)
Answer: A time series is a chronologically ordered sequence of statistical observations recorded at uniform time intervals. Mathematically, it is expressed as $Y = f(t)$, where $t$ represents time and $Y$ represents the dependent business variable under investigation.
Answer: In the Additive Model $Y = T + S + C + I$, components are assumed mutually independent and expressed in original physical units with constant amplitude. In the Multiplicative Model $Y = T \times S \times C \times I$, components are interdependent, and seasonal/cyclical variations are proportional ratios whose absolute amplitude expands or contracts with the trend.
Answer: In an Additive Model, the algebraic sum of seasonal variations over an annual cycle of 12 months or 4 quarters must equal zero: (\sum_{i=1}^{k} S_i = 0).
Section B & C: Comprehensive Questions (10 Marks Each)
Model Answer Outline:
- Introduction & Definitions: Define time series (Croxton & Cowden, Ya-Lun Chou) as a function of continuous time $Y = f(t)$. State the 4 components $T, S, C, I$.
- Additive Decomposition: Provide the formula (Y_t = T_t + S_t + C_t + I_t). Detail assumptions: mutual independence, identical physical units, constant amplitude of seasonal oscillations, and annual sum property (\sum S_i = 0).
- Multiplicative Decomposition: Provide the formula (Y_t = T_t \times S_t \times C_t \times I_t). Detail assumptions: proportional interdependence, dimensionless index multipliers, expanding trumpet wave pattern, and annual mean property (\frac{1}{k}\sum S_i = 1.0).
- Comparative Matrix: Draw a 6-row comparison table contrasting governing formula, units, amplitude behavior, deseasonalizing formula, and practical suitability.
- Why Multiplicative Dominates Corporate Practice: Explain economic realities: growing businesses naturally experience expanding seasonal revenue swings (e.g., Maruti festive sales or Amazon Diwali GMV) that scale with company size rather than remaining constant absolute units.
Discussion & Questions
0 CommentsAcademic insights, questions, and conceptual clarifications from students & faculty.
No questions or comments yet
Have a doubt about this topic, an exam tip, or a conceptual perspective? Start the discussion below!
Leave a Comment / Ask a Question
Your email address will not be published. Required fields are marked *